Research
Inside the Bullseye
Like it or not, everyone is now exposed to data center investment and politics. This report helps you understand why and what to do about it.
Research
Like it or not, everyone is now exposed to data center investment and politics. This report helps you understand why and what to do about it.
Willie Nelson probably doesn’t know your company’s name or what’s on your risk register. But this summer, in a post from deep in the heart of Texas, the famous singer described the data centers driving last quarter’s GDP as “loud, water thieving, [and] light polluting.” Millions of his fans liked and shared his urge to “fight against data centers invading our land.” On the opposite political and geographic end of the country, 70% of Michigan respondents across the partisan spectrum are now opposed to data centers. Most consequentially, opposition hasn’t stopped at social media or surveys; there are now nearly 150 moratoria pausing development across Michigan alone and 1,000 development pauses affecting projects across the nation.
Every project that ends up delayed or denied is a business and reputational risk for a global web of companies. Yet despite the remarkably fast and furious pushback that’s emerged as the midterm’s hottest topic, most firms still see this issue as remote. Ask the average board member or executive where data center politics sit on their risk register, and they’ll look at you with confusion. At face value, you might forgive them for the omission; historically, risk related to this issue was rare, reserved domestically for crypto and blockchain companies. In our comprehensive review of moratoria and public company communication from the last decade, examples were concentrated on Bitcoin miners or isolated abroad to Singapore or Amsterdam. Nobody on Wall Street, K Street, or Main Street cared.
Things began to change in 2022, as data center REITs and operators like Digital Realty Trust and Applied Digital began to disclose these issues as Risk Factors in their annual filings: “Governmental authorities have in the past sought to restrict data center development based on environmental considerations. […] Moratoria on data center construction could hinder our ability to construct new data centers.” Still, there were just six total disclosures across SEC filers in fiscal 2024.
Unique companies per fiscal year with opposition or moratorium language within 1,200 characters of a data center mention in 10-K, 10-Q or 20-F filings. Source: authors’ analysis of EDGAR.
Fast forward to today, and Exhibit 1 above shows that the conversation has clearly gone critical. So far in 2026, dozens of bellwether brands like Nvidia and Oracle have highlighted data center politics in their filings or investor calls. In truth, no one ever doubted that these companies were exposed to the AI buildout. Instead, the question worth asking today is why so many other firms are not discussing the pushback. Brookings estimates that approximately $10.3 trillion will be spent from 2025 to 2032 on the “AI buildout.” While many of those dollars will be captured by a small number of vertically-integrated names, trillions more will flow broadly through the fractal web of supply chain relationships.
Set against that backdrop, formal reporting is quiet in a way that implies misunderstanding of the risk. Of about 6,400 companies that filed a 10-K for fiscal 2025, 27% mention data centers directly and nearly 60% mention artificial intelligence. Thus, many of these companies are exposed to data center politics in some way, yet less than 1% disclose any exposure to the risk.
Unique filers of Form 10-K for fiscal year 2025, filed through 20 September 2026; a filing counts once regardless of how often the term appears. Full-text search of the edgar-rs store; “data centers” includes all spellings; the last two rows require the term within the same filing as a data-center mention.
The web of exposure
For boards, it’s critical to remember that this fractal web of supply chain relationships carries more than money; it also carries the consequences of every approved, delayed, or failed project. If a community in Michigan sues Oracle over discharges into the Saline River, project delays flow down the metaphorical river to harm or help Oracle’s suppliers and competitors. Seemingly-local fights over water, noise, or political process can postpone access to compute capacity, delay or cancel equipment orders, strand construction crews and equipment, or stress a bank’s credit portfolio. Conversely, every approved project or facility that comes online can drive up local labor costs or push out timelines for chips or raw materials.
Insurers and global reinsurers, normally the most forward-looking actors, are taking notice. Swiss Re, for example, recently highlighted the concentration of value in large data centers and how difficult it is to track across carrier programs and insureds. This concern is even translating into frictions for developers, who face uphill battles to insure projects in accordance with credit covenants.
The greatest battle of them all, however, is unfolding across polls this November. Political opinion travels back through the same web, faster than even the money. Ratepayers seek protection from higher utility bills, while developers and utilities lobby state and local officials for queue priority, tax incentives, or favorable land use regulation. Every small town’s dispute is at once a mayor’s recall, a hot potato in the state capitol, a key issue for swing voters deciding the fate of the US Senate, and a litmus test for Sino-US relations.
Your company likely has no intention of taking a public position on any of those topics, but your contracts and costs are exposed whether you like it or not. At this scale, everyone is inside the bullseye.
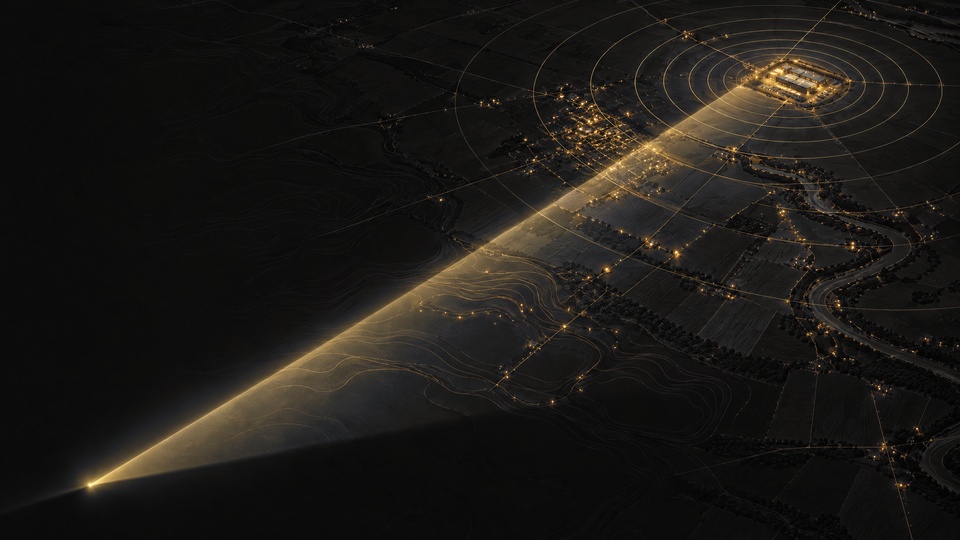
Thankfully, the bullseye metaphor is more actionable than just aphorism. Imagine your risk exposure as concentric rings, and you quickly develop a framework like the Data Center Exposure Bullseye shown in Exhibit 3 below.
Source: authors’ framework. Categories can overlap. Directness of connection is not a measured ranking of financial risk; concentration, contractual obligations and control determine vulnerability.
If you’re a hyperscaler, developer, or other project owner, we don’t need to tell you that you sit at the center of risk and responsibility; your name is already plastered across every news article and hand-drawn cardboard sign at town hall. While owners face the most direct and obvious exposure, they also wield the most influence over the direction of projects and their relationship with community stakeholders.
That influence is worth the most early for all parties involved. Not all opposition issues are remediable, but many of them are. Hyperscalers and developers who can unbundle community concerns stand a chance to engage constructively on topics like local economic and environmental issues before positions harden and trust is lost. More fundamentally, more attention is now being paid to siting, capacity, and timeline; the best way to reduce risk here is to improve the way that planning, siting, and construction happen in the first place.
Risk managed at the owner level is also risk managed for everyone else downstream. But most of us aren’t owners.
Instead, many firms are direct or indirect counterparties, whose role combines both substantial exposure with limited control. They come in three types.
The first type contains the large and diverse group of firms that span much of the physical economy, from the well-known chip manufacturers to the construction and service industries and banks, asset managers, and insurers who fund them. These are the people who largely capture those trillions as revenue or finance them in debt or equity markets.
The second type buys the computing capacity that the first is supposed to deliver. Every Fortune 500 firm building a strategy that depends on tokens from OpenAI, Anthropic, Google, or integrators like Palantir and Salesforce, counts themselves among this group.
The third type may look more like you: a firm that buys or sells goods or services to the first two types, or someone one or two degrees removed. Some of these firms have an inkling that they are connected to the web, but many do not. And even those firms who know they benefit also pay elsewhere; the cost of memory in every construction manager’s laptop has practically doubled as suppliers like Micron have dedicated their output to AI.
We will likely never know how much of that $10 trillion is spread across these firms - catering companies, component manufacturers, car rentals, engineering consultants, and myriad more - but there is no question that many fortunes will rise or fall on trickle-up and trickle-down data center dollars.
Rarely does one ask a hyperscaler, “won’t you be my neighbor?” Yet whether you are an individual or a firm, you will likely find yourself sharing a grid, water supply, labor market, or political environment with a contested data center sooner than later. Neighbors sign no contract and often have no agency alone, but that does not mean that they bear no burden or have no voice together.
For many firms, the first and largest touchpoint will be energy. As the largest source of new US demand for electricity, data centers are forcing many electron-hungry industries to compete for access and chase on cost. While political attention has thus far focused primarily on the impact to individual ratepayers, firms too have a voice before state legislatures and public utility commissions. And considering the fact that many of these impacted “neighbor” firms are also large employers like manufacturers, the situation results in an uncommon opportunity for alignment across a broad swath of political actors and residents.
With over 1,000 data center projects under proposal or development across every state in the union, we are all neighbors broadly to these projects. Yet from a societal view, many firms are best characterized as onlookers with no material project or resource dependency today. They may still be exposed through broader financial market dynamics or changes in public attitudes toward AI, but that does not justify putting every decision through this lens.
That said, it only takes a day for every onlooker to become a neighbor or counterparty. That service provider who grew over decades on your steady partnership might no longer have time for you when a hyperscaler knocks. And for any industry or business that relies on political status quo or stable energy prices, the writing is already on the wall. Be vigilant, if not more.
It no longer matters whether or not your firm is a data center developer itself. The threshold question is whether a change in the priority, pacing, and politics of data center development can materially affect your revenues, costs, financing, or strategy. And once you frame the issue that way, the burden on most boards is not really whether but how much?
The good news is that if you bring the bullseye into the boardroom, you’ll see that you likely already have many of the tools necessary to measure and monitor these risks. Can you list your contracts and counterparties? Are you on top of political dynamics in the states and countries you do business in? Do you regularly game out what happens if key customers, suppliers, or materials end up on the front page tomorrow? The north star for your strategy, as ever, is to map out that constellation of actors and relationships so you can stay at least one step ahead.
While Willie Nelson may be worried about data centers outshining the night sky, Johnny Cash might offer boards the better advice. You don’t have to be a data center developer to walk the line, just keep your eyes wide open all the time.
The full report
The full 23-page edition adds what to watch over the next six months:
Work with Unruly
To book a consultation with the authors or commission a custom Bullseye report for your company, write to sales@unrulycorp.com.
Coming soon from Unruly Ideas: The data center and AI election. Where 1,215 federal and statewide candidates in all 50 states stand on data centers and, separately, on artificial intelligence. Subscribe to receive it on release.
Sean West is CEO of AI-native political risk firm The Unruly Corporation and author of Unruly: Fighting Back when Politics, AI and Law Upend the Rules of Business (Wiley 2025). Michael Bommarito is Chief Innovation Officer at The Unruly Corporation, President at the ALEA Institute, and author of Server Country: AI, Power, and the Remaking of Rural America (2026).